
Commercialization
203 articles
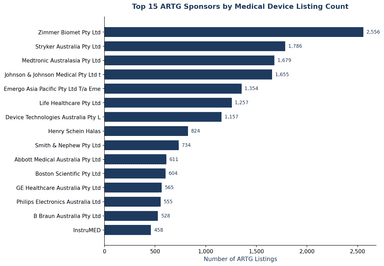
Australia ARTG Sponsor Map: Who Controls Market Access for 63,000 Devices?
Analysis of Australia's ARTG reveals 3,377 sponsors managing 63,131 device listings — top 10 sponsors control 22%, and Emergo Australia represents 375 overseas manufacturers.
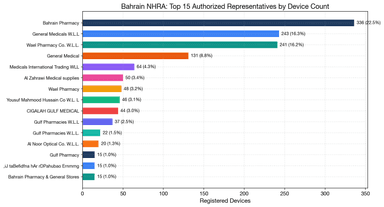
Bahrain NHRA: 3 ARs Hold 55% of Devices — Small GCC Market Channel Lock-In
Bahrain NHRA device database analysis: 62 ARs manage 1,491 devices, top 3 hold 55%, all tracked licenses expired, and manufacturer-AR lock-in is high. GCC channel strategy implications.
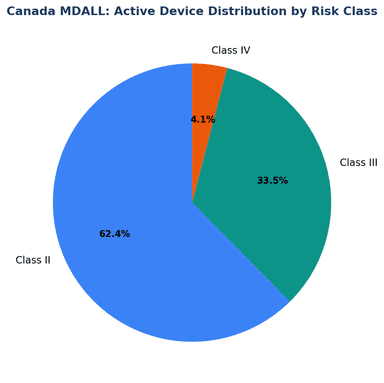
Canada MDALL Class III/IV Analysis: US Companies Hold 48% of High-Risk Listings
US companies hold 48% of Canada's 57,000 Class III/IV MDALL listings. Median device age is 9.7 years and 49% of devices are over a decade old. Full data analysis.
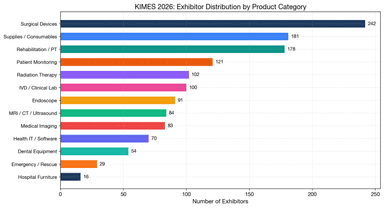
KIMES 2026: 977 Exhibitors, 78% Korean, Surgical Leads — Korea Export Push
KIMES 2026 exhibitor analysis: 977 companies, 78% Korean, surgical devices lead at 259 exhibitors, 94% export-ready. China tops international pavilion with 81 companies.
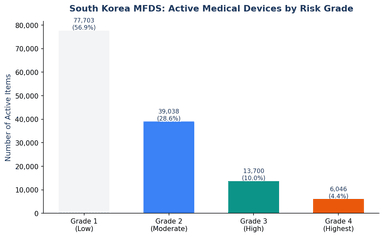
Korea MFDS: J&J, Medtronic, Stryker Dominate High-Risk Device Imports
Korea MFDS data shows 13,117 licence holders manage 273,672 registrations. Top 20 holders control 14.4%. US firms dominate Class III/IV imports at 30.4%.
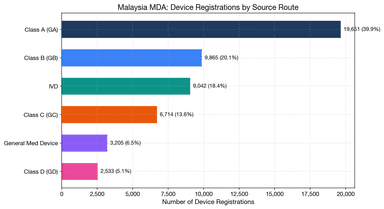
Malaysia MDA: 2,462 Establishments, 23% Expiry Cliff, J&J at 58% Renewal
Malaysia MDA 49,198-row device dataset reveals 2,462 establishments with top-20 concentration at 18.7% and 11,438 devices expiring by end 2027. Data-driven establishment selection insights.
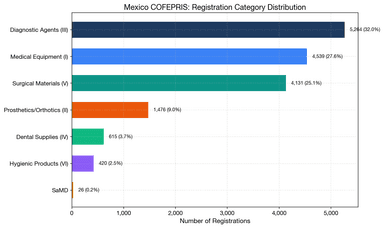
Mexico COFEPRIS Registration Holders: 5,286 Holders and the 2024 Volume Surge
Analysis of Mexico's 16,473 COFEPRIS registrations reveals 5,286 holders, 60% single-registration, diagnostics dominance at 37%, and a 2024 record peak.
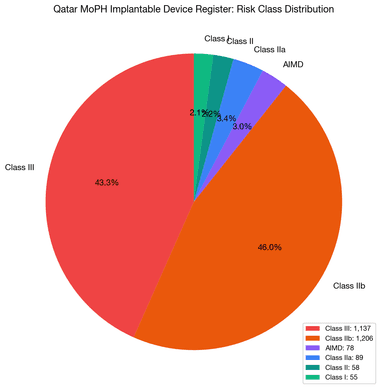
Qatar's 2,623 Implantable Devices: 62% in 20 Suppliers, Lebanese Lock-In
Qatar MoPH implantable device register: 2,623 devices, 171 suppliers, top 20 control 62%. Lebanese distributor dominance and single-supplier manufacturer lock-in analyzed.
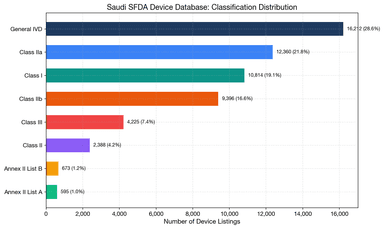
Saudi SFDA AR Concentration: 1,608 ARs, 35% in 20 Hands, 13,700 Expiry Cliff
Saudi SFDA 56,737-row device database: 1,608 ARs, top-20 concentration at 35.4%, and 13,717 devices expiring 2026-2027. Data-driven AR selection insights.
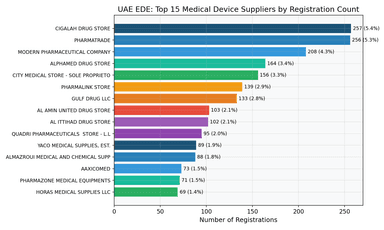
UAE EDE: 10 Suppliers Control a Third of All Medical Device Registrations
UAE EDE data shows 10 suppliers control 33.7% of 4,793 medical device registrations. Cigalah, Pharmatrade lead. US tops country of origin at 16%. Dubai holds 63.5% of registrations.
FDA Medical Device Registration: Step-by-Step Process from Classification to Market
Step-by-step FDA medical device registration — classification, 510(k)/De Novo/PMA pathways, establishment registration, device listing, FY 2026 fees, and post-market obligations.
Dermal Fillers vs Cosmetics vs Medicines: Hong Kong Borderline Classification After GN-00
How Hong Kong classifies injectable dermal fillers at the borderline between medical devices, cosmetics, and medicines — and why the May 2026 GN-00 update matters for your product.
Hong Kong Dermal Filler MDACS Listing Strategy: LRP, Docs, Importers, Procurement
Guide to listing injectable dermal fillers under Hong Kong MDACS after the May 2026 GN-00 update: LRP, technical dossier, importer controls, adverse event reporting, and procurement.
Hong Kong MDACS GN-00 Update: Why Injectable Dermal Fillers Are Now Medical Devices
On 13 May 2026, Hong Kong MDD updated GN-00 to classify injectable dermal fillers as medical devices under MDACS. What changed, why it matters, and what manufacturers must do.
Embecta-Owen Mumford $201M Deal: Auto-Injectors and Drug Delivery
Analysis of Embecta's Owen Mumford acquisition, including deal terms, Aidaptus auto-injector technology, diabetes business diversification, and GLP-1 drug-device strategy.
Connected Autoinjectors and Smart Pens: Drug Delivery Pathways in 2026
Regulatory guide to connected autoinjectors and smart pens, covering FDA 510(k), De Novo, EU MDR classification, SaMD accessory issues, cybersecurity, and human factors.
Ecuador ARCSA Medical Device Registration Guide: 2026 Requirements
Guide to Ecuador ARCSA registration for medical devices and IVDs under the April 2026 rules, covering classification, documentation, fees, timelines, and post-market obligations.
Jordan JFDA Medical Device Registration: Requirements, Process and Timeline
Guide to registering medical devices and IVDs with Jordan's JFDA, covering classification, documentation, process steps, fees, timelines, authorized representatives, and post-market obligations.
UK MHRA 2026 Overhaul: CE Mark Recognition, DORS Fees and Clinical Trials
Overview of MHRA's 2026 device reforms, including CE mark recognition, DORS fees, clinical trial changes and manufacturer compliance steps for Great Britain.
ASC Expansion 2026: CMS Final Rule and Medtech Commercial Strategy
How the CMS CY 2026 OPPS/ASC Final Rule adds 573 procedures, phases out inpatient-only limits, expands device payment opportunities, and reshapes medtech commercialization.